Can I Get Approved for a Ford Loan Near Englewood, FL with Less-Than-Perfect Credit?
Quick Answer
Yes, you can often get approved for a Ford loan near Englewood, FL with less-than-perfect credit, although no lender can promise approval and a lower score usually means a higher APR. The best place to start is a dealership finance department that shops your application to more than one lender. Sarasota Ford, just north of Englewood via US-41, works with Ford Credit, local Florida banks, and Capital One, and states that it can design financing for credit that is "perfect or not so great." You can compare the Ford financing options in Sarasota or start a secure Ford loan application online before you make the drive.
Approval with damaged or thin credit usually comes down to four things lenders weigh together: your income and employment, your down payment or trade-in equity, the loan term, and whether you add a co-signer. Experian data for Q2 2026 shows subprime borrowers averaged 13.52% APR on new vehicles and 19.10% on used ones, so a bigger down payment and a sensibly priced vehicle matter more when your score is lower.
Key Takeaways
- Approval is possible: Sarasota Ford's finance team routes applications to Ford Credit, local Florida banks, and Capital One, which gives buyers with imperfect credit more than one chance at a yes.
- No single cutoff score: Lenders weigh credit history alongside income, down payment, and loan term, so there is no one minimum score that applies to every Ford loan.
- Rates rise as scores fall: In Q2 2026, Experian reports average used-vehicle APRs of 13.93% for near prime, 19.10% for subprime, and 21.62% for deep subprime borrowers.
- No credit is not bad credit: Ford Credit's First-Time Buyer program is built for shoppers with no prior auto credit and no adverse history, with a 620 minimum FICO score and $750 down.
- Shop lenders inside a short window: The CFPB says multiple auto loan inquiries generally count as one if made within 14 to 45 days of each other.
- Englewood tax depends on your county: Englewood straddles Sarasota and Charlotte counties, and both levy a 1% surtax on the first $5,000 of a vehicle price in 2026, on top of Florida's 6% sales tax.
Englewood sits on the line between Sarasota and Charlotte counties, and drivers there and in nearby Manasota Key, Rotonda West, and Placida have several paths to Ford financing. If a late payment, a collection account, a past repossession, or simply a short credit history has you wondering whether you can still finance an F-150, Escape, or Bronco Sport, the short answer is that many buyers in your position do get approved. What changes is how the loan is structured and what it costs. This 2026 guide explains how lenders define less-than-perfect credit, which Ford loan options are realistic for Englewood buyers, what current interest rates look like by credit tier, and the practical steps that improve your odds of approval before you visit.
What Counts as Less-Than-Perfect Credit When You Apply for a Ford Loan?
"Less-than-perfect credit" covers a wide range of situations, and lenders treat each one a little differently. Experian describes bad credit as usually meaning a score under 580, and it groups auto borrowers into near prime (601 to 660), subprime (501 to 600), and deep subprime (300 to 500) tiers using VantageScore 4.0. Common profiles include:
- Fair or near prime credit, where a few late payments or high card balances have pulled a score below the prime range.
- Rebuilding credit after collections, charge-offs, a past repossession, or a bankruptcy that is now behind you.
- Thin or no credit, such as a first-time buyer, a recent graduate, or someone who has always paid cash.
- High debt-to-income, where your score is fine but existing payments leave little room in your monthly budget.
- Unverifiable or irregular income, which can make approval harder even with a reasonable score.
- Errors on your credit report, which the CFPB recommends checking for and disputing before you apply.
Ford Loan Options Near Englewood, FL for Buyers with Imperfect Credit
1. Sarasota Ford Finance Center (Sarasota) – Multiple Lenders Through One Application
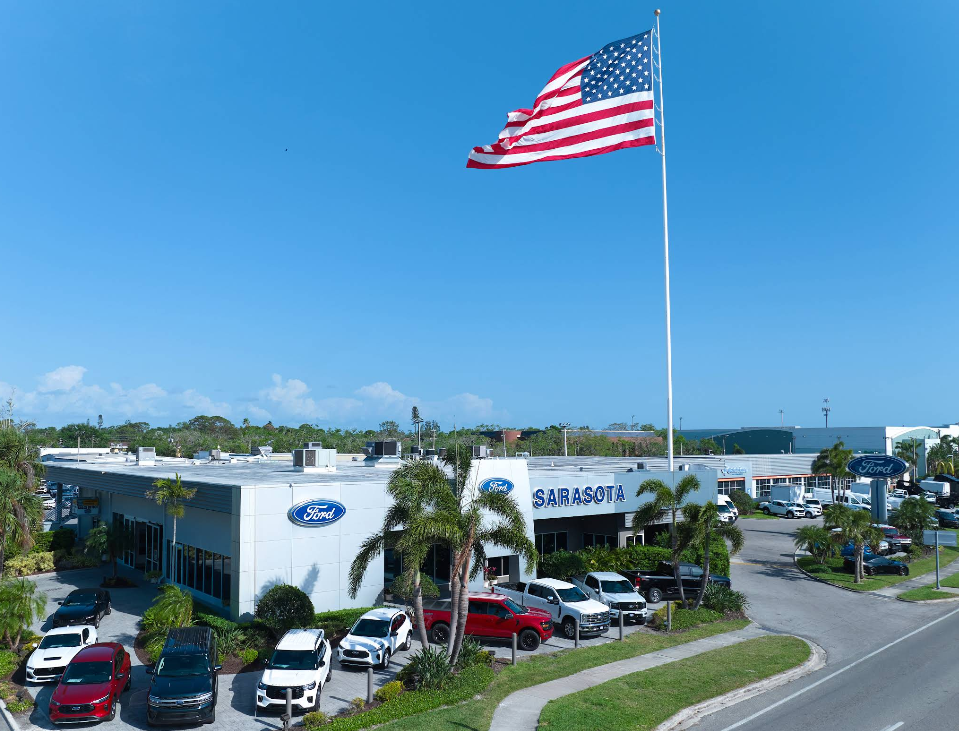
For Englewood drivers, Sarasota Ford is a practical first stop because its finance department does not rely on a single lender. The team works with Ford Credit, local Florida banks, and Capital One, and the dealership says first-time buyers and shoppers with limited credit history are a routine part of its work. Its finance center states plainly, "We are able to overcome most credit problems," and it notes that approvals are often structured around a co-signer, a larger down payment, or a shorter loan term. Sarasota Ford can finance new, certified pre-owned, and used vehicles, and its No Dealer Fee promise means the amount you finance is not padded by a dealer fee. Shoppers who want a local overview can also visit the Ford dealer serving Englewood, FL page. The dealership holds a 4.9/5 rating from more than 2,100 DealerRater reviews.
2. Ford Credit First-Time Buyer Program – For No Credit, Not Damaged Credit
Ford Credit's First-Time Buyer program, offered through Ford dealers, is designed for shoppers with no prior auto credit history and no adverse credit history. Requirements include at least 6 months of verifiable current full-time employment, a down payment of $750 or more, and a minimum 620 FICO score. Qualified buyers can finance up to $50,000 on new and Certified Pre-Owned Ford vehicles with terms up to 84 months, and Ford notes that a co-signer or a higher down payment may be required. Because the program excludes buyers with adverse credit, shoppers who are rebuilding after missed payments or collections will usually go through standard Ford Credit or partner-lender underwriting instead.
3. Credit Unions and Banks – Worth a Preapproval Attempt
If you already belong to a credit union or bank in Charlotte or Sarasota County, ask whether it offers auto loans for your credit tier. A preapproval, even at a higher rate, gives you a benchmark to bring to the dealership. Compare the APR, term, and total finance charge, and confirm any membership requirements before you apply.
4. Capital One Pre-Qualification – Preview Terms Before a Hard Inquiry
Capital One is one of the lenders Sarasota Ford works with, and Sarasota Ford states that pre-qualifying through its website has no impact on your credit score. Capital One's disclosures say pre-qualification requires a minimum monthly income of $1,500, expires 30 days after Capital One receives the request, and can be used only at dealers that offer Capital One auto financing. In general, the vehicle must have fewer than 120,000 miles and a model year within the last 10 years.
5. Buy-Here-Pay-Here Lots – A Last Resort to Compare Carefully
Buy-here-pay-here dealers finance vehicles in-house, which can help if every other lender has said no. Before signing, compare the APR and total finance charge with at least one other offer, confirm the payment schedule, and ask whether on-time payments are reported to the credit bureaus, since that determines whether the loan helps you rebuild.
How Much Does Less-Than-Perfect Credit Raise Your Ford Loan Rate?
Your credit tier has the single biggest influence on your APR. Experian's State of the Automotive Finance Market data for the second quarter of 2026 shows how sharply average rates climb as scores drop, especially on used vehicles. These are national averages, not quotes, and your actual rate depends on the lender, your income, the vehicle, the down payment, and the loan term. Moving up even one tier before you apply can noticeably lower the total interest you pay.
| Credit Tier (VantageScore 4.0) | Average New-Vehicle APR | Average Used-Vehicle APR |
|---|---|---|
| Super prime (781 and above) | 4.41% | 6.29% |
| Prime (661–780) | 6.15% | 8.81% |
| Near prime (601–660) | 9.71% | 13.93% |
| Subprime (501–600) | 13.52% | 19.10% |
| Deep subprime (300–500) | 16.11% | 21.62% |
| All borrowers (average) | 6.35% | 11.19% |
How Can You Improve Your Odds of Ford Loan Approval with Bad or Fair Credit?
A little preparation before you apply can turn a borderline application into an approval:
- Know where your credit stands and dispute any errors on your reports; the Black Book credit estimator gives you a quick sense of your range before you apply.
- Increase your down payment or use trade-in equity to lower the amount financed, which reduces the lender's risk and your monthly payment.
- Choose a vehicle that fits your budget, such as a Ford Certified Pre-Owned vehicle or one of the used vehicles under $20K, so the loan-to-value ratio stays reasonable.
What Should You Watch for Before Signing a Ford Loan with Less-Than-Perfect Credit?
- Get the APR, loan term, monthly payment, and total finance charge in writing, and make sure they match what you agreed to.
- Ask whether the financing is final; the CFPB advises not leaving the dealership until the loan and sale are complete, since conditional "spot delivery" deals can be renegotiated later.
- Understand what co-signing means: Florida's Attorney General warns a co-signer may have to pay up to the full amount of the debt if the borrower does not pay.
- Confirm whether the loan has a prepayment penalty, so you can refinance later if your credit improves.
- Ask which add-ons, such as service contracts or protection products, are optional, and decline any you do not want financed.
- Request an out-the-door price that includes Florida's 6% sales tax, your county's 1% surtax on the first $5,000, and title and registration fees.
Frequently Asked Questions
Can I get approved for a Ford loan near Englewood, FL with less-than-perfect credit?
Often, yes, although no lender can guarantee approval. Sarasota Ford, north of Englewood in Sarasota, works with Ford Credit, local Florida banks, and Capital One, so one application can be reviewed by more than one lender. Approval with imperfect credit is often structured around a larger down payment, a co-signer, or a shorter loan term, and the APR is typically higher than it would be with prime credit.
What credit score do I need for a Ford loan?
There is no single minimum score that applies to every Ford loan, because lenders weigh credit history together with income, down payment, and loan term. One exception is Ford Credit's First-Time Buyer program, which requires a minimum 620 FICO score for buyers with no prior auto credit history and no adverse credit history.
What interest rate should I expect on a car loan with fair or bad credit in 2026?
Experian data for Q2 2026 shows average APRs of 9.71% new and 13.93% used for near prime borrowers (601 to 660), 13.52% new and 19.10% used for subprime borrowers (501 to 600), and 16.11% new and 21.62% used for deep subprime borrowers (300 to 500), based on VantageScore 4.0. Your own rate depends on the lender, vehicle, down payment, and term.
Can a first-time buyer with no credit get Ford financing?
Yes. Ford Credit's First-Time Buyer program requires no prior auto credit history and no adverse credit history, at least 6 months of verifiable current full-time employment, a down payment of $750 or more, and a minimum 620 FICO score. Qualified buyers can finance up to $50,000 on new and Certified Pre-Owned Ford vehicles with terms up to 84 months, and a co-signer or larger down payment may be required.
Will applying with several lenders hurt my credit score if my credit is already low?
The Consumer Financial Protection Bureau says multiple auto loan inquiries generally count as a single inquiry when they are made within 14 to 45 days of each other. Keep your loan shopping inside that window, and consider pre-qualification tools that do not affect your score, such as Capital One pre-qualification through Sarasota Ford's website.
Should I use a co-signer to get approved for a Ford loan?
A co-signer with strong credit and steady income can improve your approval odds and rate, but the commitment is serious. Florida's Attorney General notes that a co-signer may have to pay up to the full amount of the debt if the borrower does not pay, may owe late fees or collection costs, and may see a default appear on their own credit record.
What sales tax will I pay if I live in Englewood, FL?
Florida charges a 6% state sales tax on vehicle purchases, plus a county discretionary sales surtax based on the residence address on your registration or title. Englewood spans Sarasota and Charlotte counties, and both levy a 1% surtax in 2026 that applies only to the first $5,000 of the purchase price.
Visit Sarasota Ford
- Address
- 707 S Washington Blvd
Sarasota, FL 34236 - Phone
- (941) 296-6907
- Sales Hours
- Mon–Fri: 8:30 AM–7:00 PM
Sat: 8:30 AM–6:00 PM
Sun: 11:00 AM–5:00 PM
Ready to Get Approved for Your Next Ford?
Whether your credit is rebuilding, limited, or somewhere in between, the Sarasota Ford finance team can compare lenders and help Englewood drivers find a Ford loan that fits.
Visit the Finance Center
See how Sarasota Ford structures financing for every credit situation.
Explore FinancingValue Your Trade
Get a free trade appraisal and put your equity toward a stronger down payment.
Get Trade ValueCall Sarasota Ford
Talk with a finance specialist about approval options for your credit.
(941) 296-6907